The Shift from Execution to Inference
Banking CIOs have lived through multiple waves of technology change: core banking modernization, the internet, and the mobile revolution. Each transition demanded heavy capital investment, organizational rewiring, and a willingness to cannibalize legacy systems that still worked. The overarching goal of these past transitions was to build faster, cheaper “execution engines”-systems designed to automate explicitly defined processes and reduce the cost per transaction. In the digital-first era, success was measured by channel effectiveness: how fast and frictionless a customer could execute a task on a mobile app or web portal.
The shift from digital-first to AI-first banking is fundamentally different. It is not just another channel or a faster way to execute existing rules. AI shifts the axis of banking technology from passive execution to active inference and orchestration. Where digital technologies required humans to conceptualize a plan, build the rules, and structure the data beforehand, AI can autonomously conceptualize an objective, dynamically harness unstructured data from anywhere, and interpret context to make real-time decisions.
Shifting from Channels to Context
Digital banking lowered the cost to serve by moving customers to self-service interfaces. AI redefines the architecture by breaking the constraints of static data models and rule-based processing:
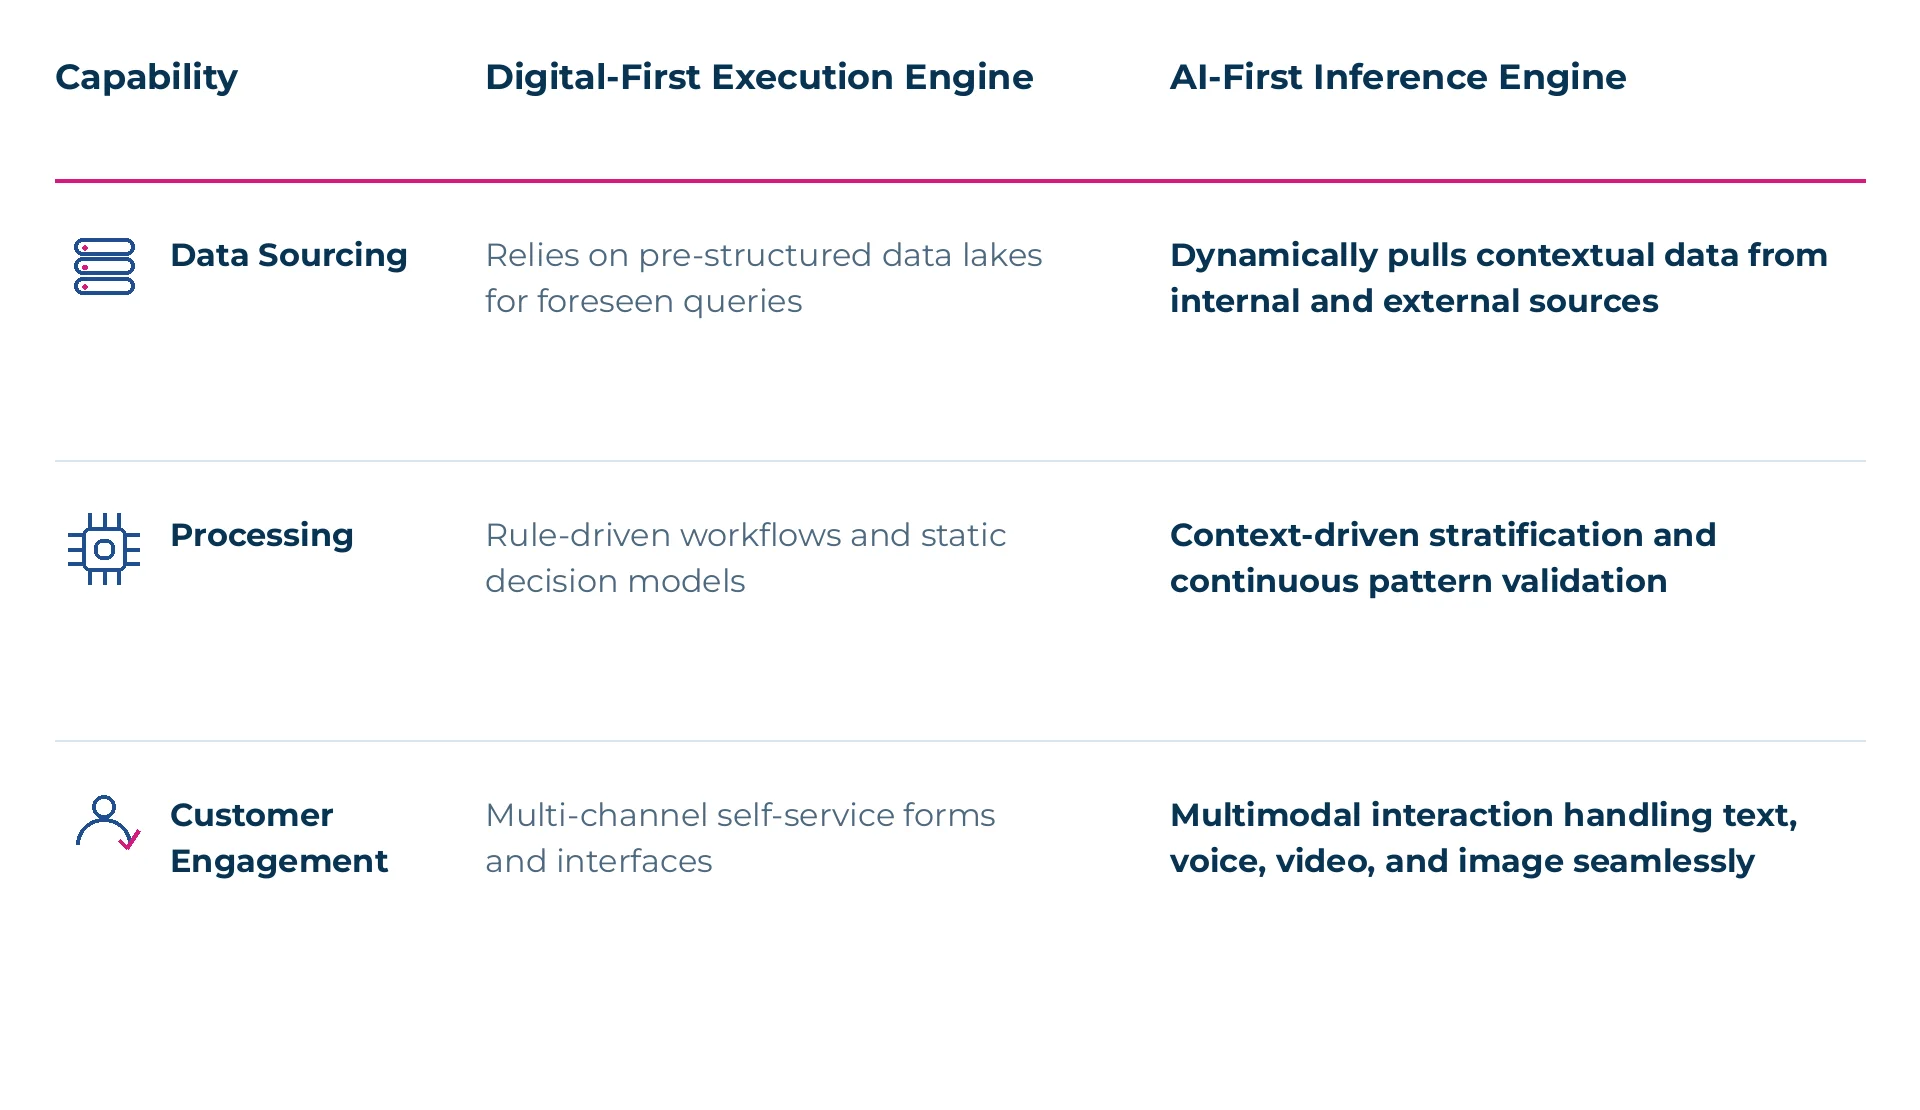
| Capability | Digital-First Execution Engine | AI-First Inference Engine |
|---|---|---|
| Data Sourcing | Relies on pre-structured data lakes for foreseen queries | Dynamically pulls contextual data from internal and external sources |
| Processing | Rule-driven workflows and static decision models | Context-driven stratification and continuous pattern validation |
| Customer Engagement | Multi-channel self-service forms and interfaces | Multimodal interaction handling text, voice, video, and image seamlessly |
Banking CIOs have lived through multiple waves of technology change: core banking modernization, the internet, and the mobile revolution. Each transition demanded heavy capital investment, organizational rewiring, and a willingness to cannibalize legacy systems that still worked. The overarching goal of these past transitions was to build faster, cheaper “execution engines”-systems designed to automate explicitly defined processes and reduce the cost per transaction. In the digital-first era, success was measured by channel effectiveness: how fast and frictionless a customer could execute a task on a mobile app or web portal.
The shift from digital-first to AI-first banking is fundamentally different. It is not just another channel or a faster way to execute existing rules. AI shifts the axis of banking technology from passive execution to active inference and orchestration. Where digital technologies required humans to conceptualize a plan, build the rules, and structure the data beforehand, AI can autonomously conceptualize an objective, dynamically harness unstructured data from anywhere, and interpret context to make real-time decisions.
1. Customer Servicing: From Journey Mapping to Journey Intelligence
In the digital era, customer servicing centered on journey mapping. Banks invested heavily in UI/UX design to identify pain points and remove friction from digital interfaces. However, this was largely an operations problem solved by pushing the burden of data entry onto the customer through “self-service.”
AI makes customer servicing an inference problem.
The question shifts from “Is the digital journey working?” to “How can we dynamically orchestrate the right outcome without the customer having to do the work?” This shift plays out most concretely in two areas: customer onboarding and ongoing multimodal support.
1.1 Rethinking Onboarding: Unifying Risk and Automating Context
Onboarding remains one of banking’s most expensive and fragile processes. Regulators demand absolute thoroughness, while customers demand instant access. AI reconciles this tension through three structural shifts:
Pushing Self-Service to Zero-Service:
Digital banking introduced self-service, which simply meant the customer typed in their own data instead of a bank teller doing it. Agentic AI pushes this paradigm toward “zero-service.” Through intelligent data orchestration, AI solutions proactively pull contextual information from CRM records, government registries, third-party data providers, and digital behavioral footprints. In Maveric’s recent implementations for regional banking leaders, this capability fundamentally reduced customer onboarding times from hours to just 8–10 clicks through AI-powered verification and account opening.
Contextual Status Validation:
The traditional delay in onboarding is the human effort required to review documents, validate addresses, and chase down missing information based on rigid checklists. Agentic workflows now handle this validation continuously. Rather than relying on static, rule-based processing, AI uses contextual stratification. It evaluates the specific risk profile of the customer in real-time, instantly straight-through processing low-risk applicants while intelligently routing high-risk anomalies to compliance officers with a summarized context of why the escalation occurred.
Unified KYC, AML, and FCM Infrastructure:
Historically, Know Your Customer (KYC), AML, and Financial Crime Management (FCM) have been managed as separate compliance programs with siloed tooling. This separation creates massive data redundancies and high false-positive rates. AI enables the convergence of these disciplines. By harnessing plural sets of unstructured and structured data concurrently, AI creates a unified risk infrastructure. Maveric consistently observes that banks building this KYC-AML convergence as a unified infrastructure at the outset realize substantially higher fraud-loss reductions and save millions in integration debt later.
1.2 Customer Support: The Shift to Multimodal Engagement
The traditional contact center model—even augmented by first-generation, rule-based chatbots-is a liability. Chatbots were essentially rigid decision trees; if a customer’s problem fell outside the programmed rules, the bot failed, leading to customer frustration and an inevitable human escalation.
AI resolves this by introducing true multimodal capabilities. Digital banking merely gave customers multiple separate channels. AI gives banks multimodal intelligence capable of seamlessly processing and pivoting between text, voice, image, and video within a single interaction.
If a customer is struggling to understand textual instructions, the AI does not just repeat the text-it interprets the customer’s confusion and dynamically switches modes, generating a personalized visual walkthrough. Furthermore, when an escalation is necessary, AI transfers complete context, including sentiment analysis and recommended resolution steps. For example, by deploying an innovative AI-driven Agent Assist solution and an Intelligent Knowledge Management platform, Maveric Systems enabled a global bank to dramatically optimize operations, pushing their First Call Resolution (FCR) rate to an industry-leading 90%.
First Call Resolution (FCR) rate to an industry-leading
2.0 Hyper-Personalization: Breaking the Constraints of Static Models
For years, the failure to deliver true personalization was blamed on data fragmentation. Maveric’s engagements with global banking leaders confirm that untangling core banking data from siloed CRMs is indeed a major hurdle. However, the deeper limitation was the industry’s reliance on human-built, static analytical models.
In the past, data scientists had to build a specific model for an anticipated outcome, load it with historical data, and run batch processes. If the context changed, the model broke.
AI flips this dynamic. It breaks the constraints of static models by acting as a dynamic orchestration engine capable of real-time conceptualization.
AI solves the personalization gap through three capabilities:
Predictive Life Stage Engagement:
Traditional Next Best Action (NBA) engines flagged product opportunities based on static demographics or a single recent transaction. AI, conversely, harnesses unlinked, plural data sets-stable salary deposits, changes in rental payments, geographic location data, and browsing behavior-to make forward-looking, predictive inferences about a customer’s life stage. Because AI does not require pre-structured data tables to find these correlations, it can identify complex combinations across millions of customers simultaneously. It moves the bank from reactive cross-selling to anticipatory engagement, identifying prime lending candidates before they begin searching for loans. Maveric notes that institutions achieving this level of enterprise-scale AI adoption realize up to 10–15% gains in revenue productivity.
Dynamic Pattern Validation and Reduced Iteration Fatigue:
In the digital era, marketing teams had to constantly A/B test campaigns, nudges, and alerts to see what worked, requiring endless manual iterations and coding adjustments. AI eliminates this human bottleneck. It continuously creates patterns, tests them in real-time, interprets the results, and autonomously refines its own recommendations. Because AI rapidly learns which specific messages and modes of communication resonate with an individual customer, it drastically reduces “iteration fatigue.” Banks no longer need to spam customers with generic alerts in hopes of a conversion. A proactive nudge is delivered precisely when the customer is most likely to act on it, fundamentally enhancing trust.
Automated Churn Prevention:
Customer churn is often preceded by subtle behavioral shifts-declining product usage, gradual balance reductions, or erratic digital engagement. While manual models struggled to weigh these disparate factors in real-time, AI continuously analyzes this unstructured behavioral exhaust. When the AI infers a high probability of churn, it does not just flag the account; it orchestrates the intervention. Low-risk candidates receive highly tailored, automated outreach, while high-value customers are routed immediately to relationship managers armed with an AI-generated brief on exactly what offers will likely retain the business.
3.0 Faster Product Releases: Automating the End-to-End SDLC
The final dimension of the AI-first CIO mandate is internal: fundamentally rethinking how the bank builds and ships software. Customer expectations and competitor product cycles are compressing rapidly. The ability to design, test, and release new banking products in weeks rather than quarters is now a baseline competitive requirement.
Initially, AI in software development was viewed merely as a “copilot”-an intelligent autocomplete tool that helped developers write code slightly faster. However, treating AI as just a coding assistant leaves massive efficiency gains on the table.
Today, generative AI and agentic workflows are capable of orchestrating the entire Software Development Life Cycle (SDLC).
3.1 Generating the Product Backlog:
Historically, deciding what to build required business analysts to survey markets, read customer feedback, analyze competitor feature sets, and manually synthesize that data into a product backlog. AI automates this conceptualization phase.
By continuously ingesting and interpreting unstructured data-app store reviews, call center transcripts, market reports, and competitor press releases-AI can accurately infer what features customers actually want and use. It can autonomously generate user stories, define technical requirements, and prioritize the product backlog based on projected business value, completely bypassing the traditional human bottleneck of requirements gathering.
3.2 End-to-End Development and Agentic Testing:
Once a requirement is conceptualized, agentic AI development models orchestrate the execution. Instead of siloed development and Quality Engineering teams passing code back and forth, AI manages the continuum.
Agentic systems generate the code while simultaneously building the unit tests, mapping integration points, and generating system documentation. More importantly, because AI maintains a holistic view of the entire codebase, it understands the contextual relationships between different systems. This mitigates the “contextual isolation” problem where AI-generated code passes a unit test but breaks the wider banking application upon integration.
Quality Engineering at Maveric Systems
Agentic AI operates across three layers
- Perception Layer Continuously monitors code commits
- Reasoning Layer Maps changes to test coverage priorities
- Action layer Executes test suites & auto-heals broken scripts
By automating the creation of edge-case scenarios, AI drastically reduces defect escape rates and compresses the time-to-market for secure, compliant software releases.
Engineering the AI-First Operating Model
The digital era asked banking CIOs to be fast, accessible, and multi-channel. The AI era asks them to be intelligent, predictive, and multimodal. This requires a profound shift in mindset: technology is no longer just an engine to execute human commands; it is an engine that conceptualizes, orchestrates, and infers.
To lead in this environment, Maveric advises CIOs to re-vision their performance metrics from purely technical indicators to multi-dimensional business outcomes: operational KPIs (turnaround time, cost), business KPIs (revenue, fraud reduction), and trust KPIs (explainability, fairness).
Stop building for foreseen queries:
Shift data architectures away from static lakes designed only for known rules. Build dynamic foundations that bring domain, digital, data, and quality engineering competencies together seamlessly.
Mandate multimodal engagement:
Move beyond isolated chatbots. Engineer customer servicing platforms that pivot between voice, text, and visual inputs based on real-time customer capability, driving First Call Resolution to new heights.
Automate the entire SDLC:
Deploy agentic workflows that span from automated requirements gathering to auto-healing test suites, ensuring velocity is matched with enterprise-grade quality engineering.
Banking has always been built on trust and efficiency. In the AI-first era, that trust is engineered not by how fast a customer can click through a form, but by how seamlessly the bank’s intelligence can anticipate their needs and orchestrate the solution.
Authored by
P Venkatesh
As the Co-founder and whole-time Director at Maveric, P Venkatesh (PV) leads the global thought leadership function aimed at shaping and promoting Maveric’s perspectives as well as expertise in the banking technology space. By building relationships with industry influencers, partners and BankTech ecosystem leaders, PV drives creation of impactful frameworks, methodologies and landscape reports that provide informed perspectives on new age technologies that shape the BankTech space.
Anoop Karumathil Melethil
Anoop has two decades of experience in conceptualizing, creating, and driving technology-focused marketing initiatives across tier 1 as well as mid-size global IT services organizations. He has built his expertise in building marketing functions from the ground up, encompassing areas including but not limited to media, public relations, influencer marketing, digital marketing, employer branding, thought leadership, brand outreach, field marketing, ABM, and internal communication.
Download the Whitepaper
From Digital-First to AI-First: The Mandate Reshaping the Banking CIO Agenda
Download the PDF